Macro Cycle

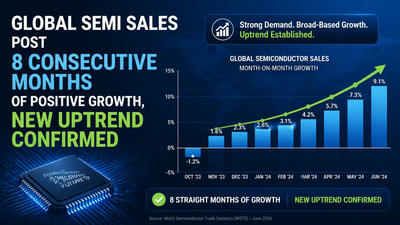
Global Semi Sales Post 8 Consecutive Months of Positive Growth, New Uptrend Confirmed

The semiconductor industry has crossed a meaningful threshold: eight consecutive months of positive year‑over‑year sales growth. That streak signals more than a short-term rebound. It suggests a structural rebalancing between demand and supply, improved capital discipline across the value chain, and the emergence of durable demand drivers that could support a multi‑quarter uptrend. For investors, OEMs, procurement teams, engineers, and policymakers, this turning point requires a shift in tactics—from defensive cost control and aggressive destocking toward selective restocking, targeted investment, and technology prioritization. This article examines why eight months matters, what’s driving the recovery, which subsegments will benefit most, the risks that remain, and practical actions stakeholders can take now.
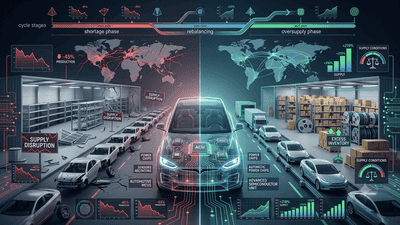
Auto Chip Supply-Demand Reversal: From Extreme Shortage to Structural Surplus

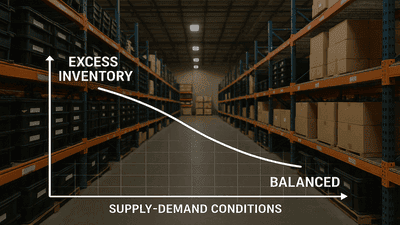
Only a few years ago, automakers around the world were halting production lines because they could not secure enough chips. Waiting lists for vehicles stretched out, component allocations were rationed, and procurement teams scrambled to find even small volumes of critical microcontrollers and power devices. Today, the picture looks very different. In multiple auto chip categories, supply has not just caught up with demand—it has overshot. What was once an extreme shortage is increasingly turning into a structural surplus.

QoQ Revenue Growth Ranking of Global Top 10 Semiconductor Firms

Quarter‑on‑quarter (QoQ) revenue growth for the world’s largest semiconductor firms offers a fast, quantitative snapshot of who is winning incremental demand at any given point in the cycle. It does not tell the whole story of structural strength, but it shows where momentum is moving in the near term—whether toward AI accelerators and advanced nodes, toward memory and storage, or toward analog and power devices tied to autos and industrial markets.

Using TSMC Monthly Revenue as a Bellwether for Global Semi Cycle Inflections

In the modern semiconductor industry, no single data point attracts more regular attention from market watchers than the monthly revenue disclosure of Taiwan Semiconductor Manufacturing Company (TSMC). Month after month, this one series of numbers sparks commentary about where the chip cycle stands, how demand for advanced nodes is evolving, and what lies ahead for everything from smartphones and PCs to AI infrastructure and automotive electronics.

Big Fund III’s 300B Yuan Allocation: Equipment, Materials, and HBM Breakdown

China’s third national semiconductor investment vehicle—commonly referred to as “Big Fund III”—marks a new phase in the country’s effort to build a more self‑sufficient and globally competitive chip ecosystem. With a planned war chest on the order of 300 billion yuan, the fund is widely expected to pivot from simply backing wafer capacity toward deeper, more targeted investments in equipment, materials, and memory technologies such as high‑bandwidth memory (HBM).

  • 1
  • 2
  • 3